The trade war is getting worse. There are tariffs everywhere.
That is also where the opportunities are.
Today I am on the positive side. Here are the sectors that shield you, the sectors taking the hit, and three companies that could do well down the road.
*Disclosure: I own Stantec (STN.TO), CGI (GIB.A.TO), Canadian Natural Resources (CNQ.TO), National Bank (NA.TO) and Royal Bank (RY.TO). I do not own Adentra (ADEN.TO). This is education, not advice. Do your own due diligence.
What Should You Do About the Trade War?
Stay invested. Waiting through tariff headlines is what cost investors in 2025, when the market fell about 10% in days and then went back into bull mode.
Some investors are afraid and decide to wait. Waiting is the worst thing you can do.
Tariffs are not news. This has been going on since Liberation Day in April 2025. The market dropped about 10% over a few days and everyone went crazy. A couple of months later, it was back in bull mode and everything was fine.
The people who sat it out in February and March missed the recovery.
This time, we do not know what will happen. Maybe it will go the other way around. That is the point. You do not know. I do not know. Your guess is as good as mine.
Waiting every single year is the worst move you can make. But you do you, I do me, and we are all good.
Should Canadians Stop Buying American Stocks?
A boycott hurts your portfolio and nobody else. The same investors avoiding US companies are reading this on an iPhone and going home to a Windows desktop.
A lot of Canadians do not want to invest in American companies anymore. I get it.
Let me play devil’s advocate for a second. You are probably watching this on an Apple phone. You are probably on Facebook. If you have a desktop at home, it runs Windows. And if you drive a Ford or a Chevy, you are not selling it to buy a Toyota.
There are moves you can make to take a stance according to your values. On the investing side, I think you hurt yourself and no one else.
What matters to me is retiring comfortably and being financially secure. That is easier with a diversified portfolio. Those are plain facts. What you do with them is yours.
Which Sectors Are Protected From Tariffs?
Energy, gold, materials and utilities. Canada is not going to stop selling oil to its southern neighbour, and power stays domestic whatever happens at the border.
Energy comes first. I would be surprised if we stopped selling oil south. The war in Iran is fuelling it, and it also helps protect against inflation.
I am not a big fan of energy. I still have to say that Canadian Natural Resources is one of my favourite stocks in my portfolio these days, on short-term performance.
Gold should do well. Materials in general too, because tariffs land on them, but a lot of materials are a necessity rather than a choice.
Utilities are power. They stay stable.
Financial services are a bit overvalued right now. Would I add more? Probably not. I am comfortable with the banks I hold, so I am not moving.
Which Sectors Take the Hit?
Consumer cyclical, consumer staples and industrials. That is also where the opportunities sit, because good businesses get sold alongside the bad ones.
Consumers get hit on both ends, discretionary and defensive. Staples too, which is the ironic part, because tariffs reach them the same way.
Everything tied to the consumer takes a hit one way or another.
Industrials is the other one, and it is already happening. That is the whole point of a tariff. Unless you move your manufacturing into the other country, you get slapped, and doing business gets harder.
You cannot move a plant within the month. It takes a lot of capital, and adapting a supply chain takes time.
That is where the digging starts.
I wrote about two other names that reached an entry point this way.
Two Quality Stocks Showing an Entry Point: Trane Technologies and AltaGas
Stantec (STN): The Engineering Firm the Market Gave Up On
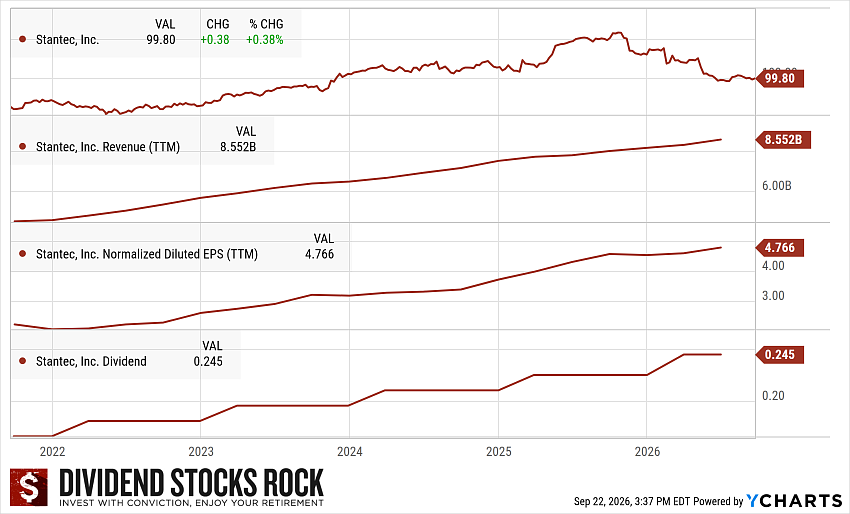
A PRO rating of 4, a Dividend Safety score of 4, and five-year growth of 13.75% on revenue and 19.25% on earnings. The business is not slowing. The stock price is.
Stantec is a big engineering firm. Its top clients have been with it for more than 25 years and use several of its services.
It is getting hit right, left and centre. It might not win contracts in the US because it is Canadian. AI could replace it, but I don’t believe it will.
So you get a lot of dark clouds and a pessimistic narrative around the name. Then you look at the facts and the financial metrics, and you see high single-digit to double-digit numbers on revenue, earnings, cash flow and the dividend.
The backlog is strong. There are plenty of orders to fill over the next 12 months, so the business is not slowing down right now.
On valuation, Stantec trades at 21.7 times earnings against a five-year average of 35.9. The forward PE drops to 14.4. The forward yield of 1.02% sits above the five-year average of 0.84%, suggesting the stock offers better income value than usual. The earnings payout ratio is under 20%.
Four metrics, all pointing the same way, on a business whose order book is full.
Long client relationships are a moat, and I have written about how that kind of moat works.
CGI (GIB.A): A Turnaround With a One-Year-Old Dividend
A PRO rating of 4, a Dividend Safety score of 4, and 12 times earnings against a five-year average of 19. The dividend only started in 2025, so the third leg of the triangle has no history yet.
CGI is a very big IT consulting firm. Most of its business comes from recurring, long-term contracts, many of which are government contracts, including with the US government.
It got hurt during that quick DOGE moment. Projects went on hold and the company saw a slowdown. The concern now is that it may not win new contracts, or may lose some of the ones it has.
That is narrative again. Do you really think anyone replaces CGI forever? It might be a rough couple of years. After that, the odds of a turnaround are decent.
I hold a small position, about 1% of my portfolio or not even. It is the riskier of the two I own. I find it an interesting play and an entertaining story to follow.
Why the Dividend Line Looks Flat on the Chart
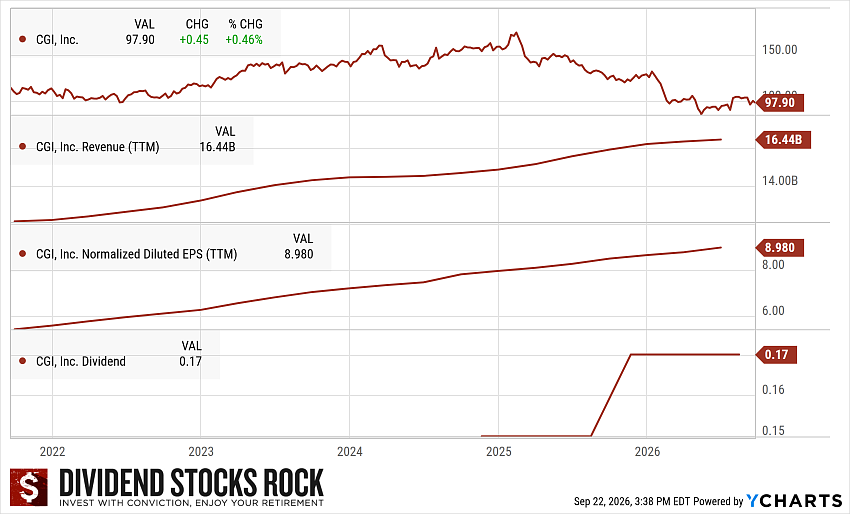
CGI paid its first dividend in 2025, at $0.15 a share. It raised that by 13% to $0.17 in November 2025, and it has stayed there since.
That is why the chart below reads the way it does. The five-year dividend growth rate shows 0.00% and the dividend line looks flat. That is not a frozen dividend. It is a dividend with one year of history behind it.
Revenue and earnings carry the triangle here, growing 6.28% and 8.29% over five years. The third leg is still being built. Judge it again in three years.
On valuation, the current PE of 12 sits well under the five-year average of 19, and the forward PE is 10. The earnings payout ratio is 8%, which leaves plenty of room for the dividend to grow once management commits to it.
Adentra (ADEN): The Small Cap Flying Under the Radar
A distributor of architectural building products worth $847 million, trading at 9 times earnings, with about 90% of its revenue earned in the US. It is also the riskiest of the three.
Start with the warning, because it belongs first. This is a small cap. The market capitalization is under $1 billion, at $847 million. That means volatility. Expect a 25% drop any day of the week.
Be clear with yourself before you look at it. You invest in that kind of stock; it drops 20%, and you smile, because you knew it would happen.
Adentra distributes architectural building products, including wood, to home builders and the construction market. It runs 81 facilities across the US and Canada.
More than 90% of its revenue comes from the US, and more than 90% of its manufacturers are in the US too. When the first tranche of tariffs came out about 18 months ago, the CEO said 90% of the business was already sheltered, because the company is based there.
That is what makes it interesting. The PE sits around 9 or 10, and it is rare to find this kind of business at that rate.
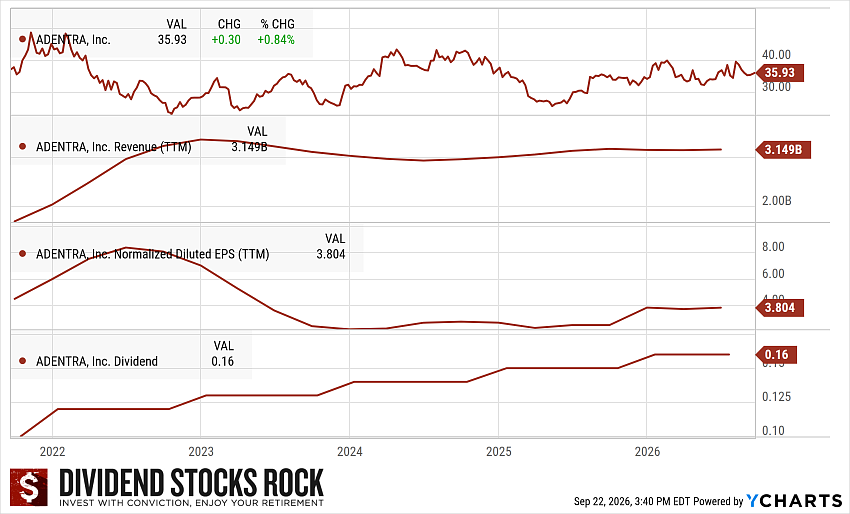
The stock price has not really moved since 2024. Two years of dead money. It dropped a lot after Liberation Day and has come back, but not by much.
Now the part that keeps it in third place. Adentra is the only one of the three that does not clear the usual bar. Its PRO rating is 3 rather than 4, and the dividend triangle has a negative leg. Earnings per share fell 5.26% over five years, while revenue grew 11.25% and the dividend grew 9.51%.
The Dividend Safety score is still 4 and the earnings payout ratio is under 16%, so the payment itself is not the worry. The earnings trend is. That is the risk I would want to be paid for here, and this price pays for a lot of it. Whether that is enough is your call.
The Verdict
A big engineering firm, a big IT consulting firm, and a small distributor of building products that does most of its business in the US.
Stantec is the quality name, priced as though its order book were empty.
CGI is the turnaround, cheap against its own history, with a dividend too young to judge.
Adentra is the cheap one, and the one where the earnings trend has to turn before the story does.
All three sit in the sectors the tariffs are hitting. That is not a coincidence. It is where the discounts are.
One last thing. You cannot buy a stock because you read a 5-minute article. Dig further, make sure you understand the business, and decide whether it fits your portfolio.
Get the Dividend Rock Stars List
The Dividend Rock Stars List tracks every Canadian and US stock with a growing dividend, updated monthly, with the metrics I screen on in one place.
Enter your name and email below to get your free copy.



Leave a Reply