Over the past 12 months, the TSX gained about 20%. Some well-known Canadian companies went the other way, with double-digit losses.
So are they falling knives that will cut you, or good buying opportunities? Some of them are in my portfolio. Around Thanksgiving, I looked at what happened over the past year and reviewed each name. The numbers below are 12-month price changes as of October 29.
*Disclosure: I own Stella-Jones (SJ), Brookfield Corporation (BN), Brookfield Renewable (BEP), Stantec (STN), Constellation Software (CSU) and CGI (GIB.A). I don’t own FirstService (FSV) or Capital Power (CPX). This is education, not advice. Do your own due diligence.
Stella-Jones (SJ): Down 15% on Squeezed Margins
I discussed Stella-Jones not too long ago. The company is struggling to show good margins, and the market doesn’t like that.
When your margins get squeezed and management tells you things will get better in 12 to 18 months, the valuation takes a hit.
The business model is still solid. Stella-Jones sells railway ties, utility poles and industrial lumber. At this point, the valuation is what hurts.
I am holding on to my shares. Being an investor means being patient sometimes.
You can read more about Stella-Jones below.
FirstService (FSV): Down 11% With a Great Business Model
FirstService is not in my portfolio, but it caught my attention. It is down about 11% over the past 12 months, even after a bounce on its third-quarter results. Over the past five years, it has been dead money in a great bull market. That is strange when you look at the business.
FirstService is the largest property manager in North America. It runs more than 9,500 community associations under multi-year contracts, which means a lot of recurring revenue. Its FirstService Brands division groups small property services companies: plumbing, closets, maintenance, restoration and roofing. They sell those services to the same communities.
The FirstService Dividend Triangle
Revenue is a line going up. It grew 12% a year over the past five years. The dividend grew above 10% a year over the same period.
The problem is earnings. EPS grew about 4% a year over five years, and it was almost flat between 2022 and 2026.
The valuation doesn’t help either. The P/E ratio sits at 35, and the forward P/E is 20, so I expect some normalization.
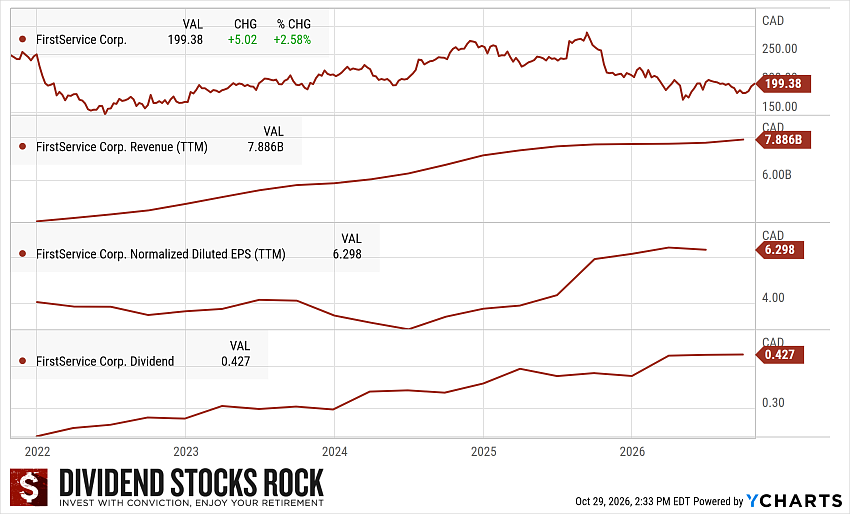
This was the first time FirstService popped up on my list, so I haven’t done much digging yet. A well-established business, recurring revenue, good dividend growth and a falling share price. It looks worth a closer look.
The Brookfields Are Testing Your Patience
The Brookfield family is down over the past 12 months:
- Brookfield Corporation (BN): down 17%
- Brookfield Asset Management (BAM): down 12%
- Brookfield Renewable (BEP): down 8%
Holding Brookfield long-term has paid off. Many people are not that patient, and they sell.
Brookfield Renewable
Higher interest rates weigh on Brookfield Renewable. Brookfield Renewable is also merging its two share classes, so BEP and BEPC are becoming one.
Every time Brookfield does this, it creates confusion. The stock market doesn’t like confusion, and the stock lags for a while. When Brookfield spun off its asset management business in 2022, the old BAM became BN, and the new BAM became the asset-light manager. The stock had a hard time, then bounced back fast.
Corporation and Asset Management
For BN and BAM, the problem is the industry narrative. Money is leaving private equity at some of Brookfield’s competitors. Investors see private funds as illiquid and a bit of a black box, and they want their money out.
The more people think that way, the more an asset manager gets squeezed. It can be forced to sell long-term investments at the wrong time and restrict withdrawals.
That is not happening at Brookfield. It is gathering more money quarter after quarter. The narrative around the industry is negative, Brookfield is doing well, and the shares are still down.
Why I Hold Brookfield Renewable
I view Brookfield Renewable like a bond with a good yield. The distribution keeps increasing, which I like.
I am 100% invested and 100% in stocks. In my mind, this is my fixed income. I don’t care much about the stock price. I care about the money coming in to stabilize the rest of the portfolio.
The AI Disruption Names
This group bothers me the most. The results are great, but the shares still haven’t gotten back on track. The AI disruption narrative is the reason.
The engineering firms, WSP Global (WSP) and Stantec, are down more than 30%. Thomson Reuters (TRI) is down 30%. CGI and Constellation Software are both down 11%.
In the U.S., some companies that suffered from the same narrative are getting back on track. I think of Salesforce, even if the rebound is not as strong. In Canada, we haven’t seen this yet.
It’s only concerning if you don’t have conviction in your investment. I am happy to have Stantec and Constellation Software in my portfolio, plus a tiny position in CGI. I am letting them ride.
As long as the numbers show up, I don’t care about the narrative. My narrative is different. Maybe I will be wrong, and that is fine. At this point, I am still investing with conviction.
Outside those groups, Capital Power (CPX) is down 11%. It is a great business, well positioned in Canada and in the U.S.
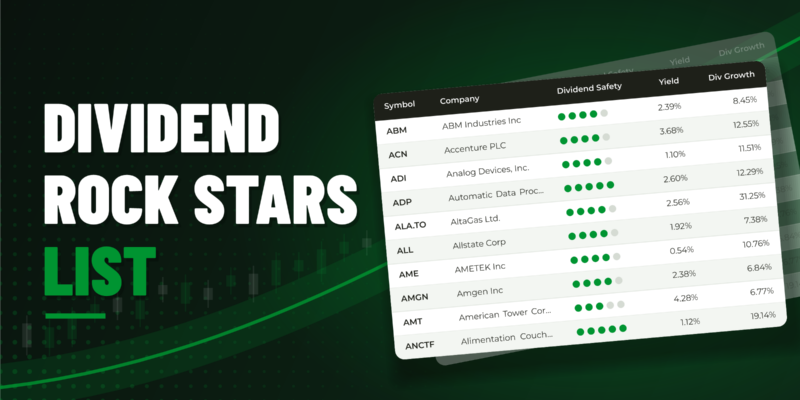
Get the Dividend Rock Stars List
If you want more ideas, my Dividend Rock Stars List is a good starting point for your research.
It is built with companies showing a positive dividend triangle: revenue, earnings and dividends all growing over the past five years. About 300 companies make the cut.
The list is updated every month and comes with my free newsletter.
Enter your name and email below to get it.



Leave a Reply